
Form 3921 instructions: A guide for US employees
Form 3921 instructions: what to report for ISO option exercises, where to find required details, filing deadlines, and how it impacts your tax return.


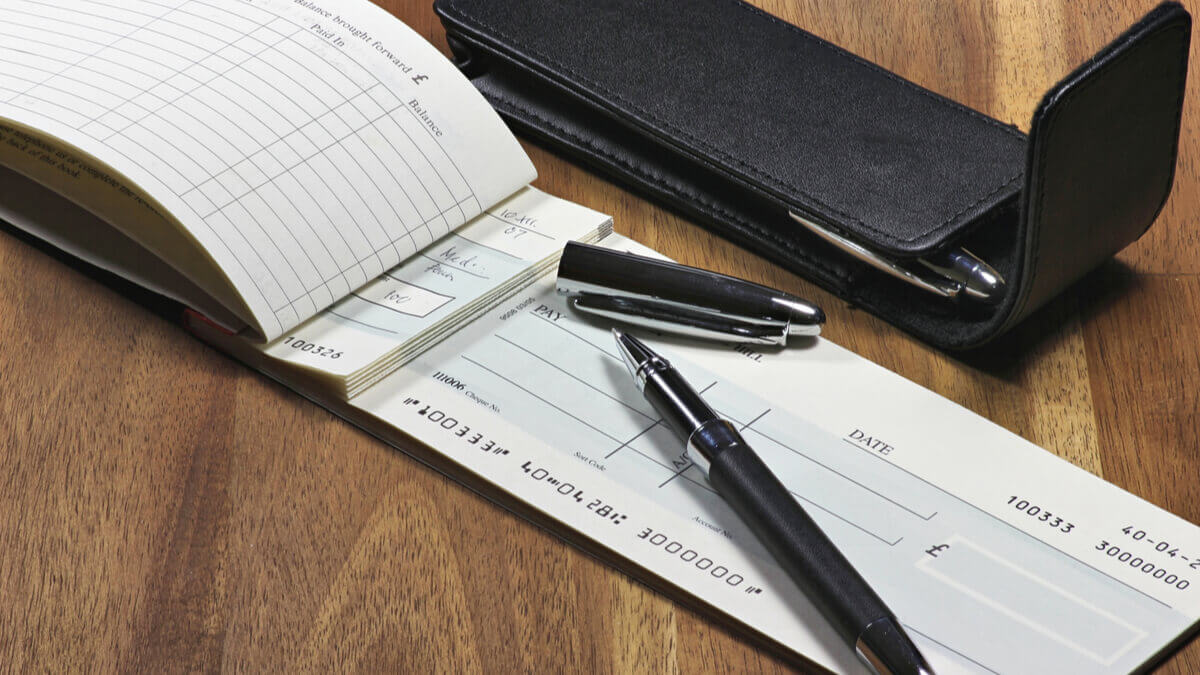
ABA stands for American Bankers Association, a trade association founded in 1875 to represent the interests of various players in the US Banking industry¹.
So how does the ABA number come into all this? Stick with us as we explain what an ABA number is, what makes it similar or different from a routing number, where you can find it and how it works.
| Are you looking for low-fee transfers overseas? Take a look at Wise – Send money internationally like a local |
|---|
An ABA – also called a routing number – is used to identify banks in the United States.
This nine-digit code helps banks in the process of transferring money domestically between accounts for different kinds of transactions, for example, direct deposit or bank transfers. ABA routing numbers are also used to identify participating financial institutions in newer payment systems such as the FedNow Service, launched by the Federal Reserve in July 2023 for instant payments⁶.
Depending on factors such as location, mergers, or business line, a bank can have several ABA numbers — up to nine in addition to its principal office routing number, as set out in the ABA Routing Number Policy².
💡 Need to send money abroad? Meet Wise, a quick and cheap way of transferring money internationally. No mark-ups on the exchange rate, you only pay what's shown to you on the screen⁵.
There are a few different ways in which you can find the ABA number you should use:
It is important to remember that a bank may have different ABA numbers. Your ABA number will most likely rely on the bank location where you opened your account. Some banks also have differing ABA numbers depending on the purpose⁴.
You may find that the ABA number assigned to wire transfers is different from the one used for electronic bill payments, or even direct deposits. If you need clarity on these matters, don't hesitate to get in touch with a customer service agent from your bank.
An ABA number in a way points financial institutions to where they should find your account. Therefore, it's no surprise that these numbers may sometimes be called check routing numbers or routing transit numbers (RTNs).
These numbers are usually printed in magnetic ink or at least in magnetic ink character recognition code (MICR) font to make them easier to detect by computers and other specialized machines. The MICR font also enables check deposit by submitting a photo of the check.
Your ABA number is usually accompanied by your account number as the information given to whoever is trying to issue a payment. The rest of the work is commonly handled by the bank, a biller or an employer.
In case a bank closes or is taken up in a merger or acquisition, you might receive new ABA numbers. Sometimes you don't have to use them right away. You may continue using the old numbers indefinitely, or at least until you request new checks and services.
According to the official ABA Routing Number Policy, the 9-digit number is made up of three components², each with its own purpose:
| Part | Purpose |
|---|---|
| First four digits (Federal Reserve Routing Symbol) | These identify the Federal Reserve district and processing office assigned to the bank. The first two digits correspond to one of the 12 Federal Reserve districts (01–12). |
| Next four digits (ABA Institution Identifier) | These uniquely identify the specific financial institution within the Federal Reserve district. |
| Last digit (Check Digit) | This is a mathematical checksum calculated from the first eight digits. It is used to validate the routing number and flag common input errors, such as transpositions or mistyping. |
In short, it's a yes and no. A routing number is a nine-digit code that banks use to identify financial institutions when transacting with them. On the other hand, an ABA is used to identify financial institutions within the US, with additional eligibility conditions.
An ABA Routing Number can be issued only to a federal or state chartered financial institution that has been determined to be eligible for a master account by a Federal Reserve Bank³.
SWIFT codes and ABA numbers are both used to identify the bank where the recipient has an account. However, while ABA numbers are used domestically, SWIFT codes are used when you transfer money internationally.
In U.S. banking terms, there is no such thing as a bank called ABA – it is rather related to ABA codes. The closest bank with the name is located in Cambodia – which is backed by the National Bank of Canada.
For many payment types, the ABA routing number found on your checkbook will be what's needed. However, as we mentioned above, it's important to know if your bank uses a different routing number for different payment types.
In this case, your wire routing number might be different to the number found on your checks.
Some banks have a different wire routing number depending on whether the payment is being received in a foreign currency, USD, or an unknown currency.
Check directly with your bank to make sure you have all the details required to allow you to receive your wire payment safely.
💡 ABA, EFT, ACH – still not sure about what they mean? Check out our glossary here.
Your wire transfer number will be a 9-digit code, like the ABA number you find on your checks. It may even be the same as the number found on your checks — but some banks choose to use different routing numbers for different types of payments.
This might mean that your wire transfer ABA number is different to the one you'll use for ACH transfers. Check directly with your bank to make sure you have the correct ABA routing number for wire transfers.
All-in-all, the ABA number is very helpful when trying to make sure that funds are sent to the right person/establishment and more specifically, the right account. They make it easier for those processing payments to pinpoint the destination in what can sometimes be a confusing web of accounts.
The ABA number also simplifies the movement of money, since these movements can be classified according to their purpose/nature. Therefore, where there are variations in rules applied in say direct deposits, electronic bill payments, etc., they can be exercised in a faster and more organized manner.
However, it is crucial to always check multiple sources and confirm with a customer support representative that you are using the right ABA number before issuing a payment.
Sources:
*Please see terms of use and product availability for your region or visit Wise fees and pricing for the most up to date pricing and fee information.
This publication is provided for general information purposes and does not constitute legal, tax or other professional advice from Wise Payments Limited or its subsidiaries and its affiliates, and it is not intended as a substitute for obtaining advice from a financial advisor or any other professional.
We make no representations, warranties or guarantees, whether expressed or implied, that the content in the publication is accurate, complete or up to date.

Form 3921 instructions: what to report for ISO option exercises, where to find required details, filing deadlines, and how it impacts your tax return.

Learn how RSU vesting is taxed in the US: Ordinary income, withholding, payroll taxes, and what to expect at tax time, with examples.

Tax implications of selling RSUs: understand withholding at vesting, capital gains after sale, reporting requirements, and tips to avoid surprises at tax time.

Report Form 3922 on your tax return: what it is, where to enter ISO stock transfer details, and how it affects income and capital gains taxes.

ISO vs RSU: understand how each works, vesting and taxes, upside potential, and which is usually better for employees at different stages.

RSA vs RSU: understand how each works, vesting and taxes, upside potential, and which is usually better for employees at different stages.


