
Buying property in Montenegro
Can US citizens buy real estate in Montenegro? Discover progressive property taxes, foreign ownership restrictions, and how to safely secure a deed.


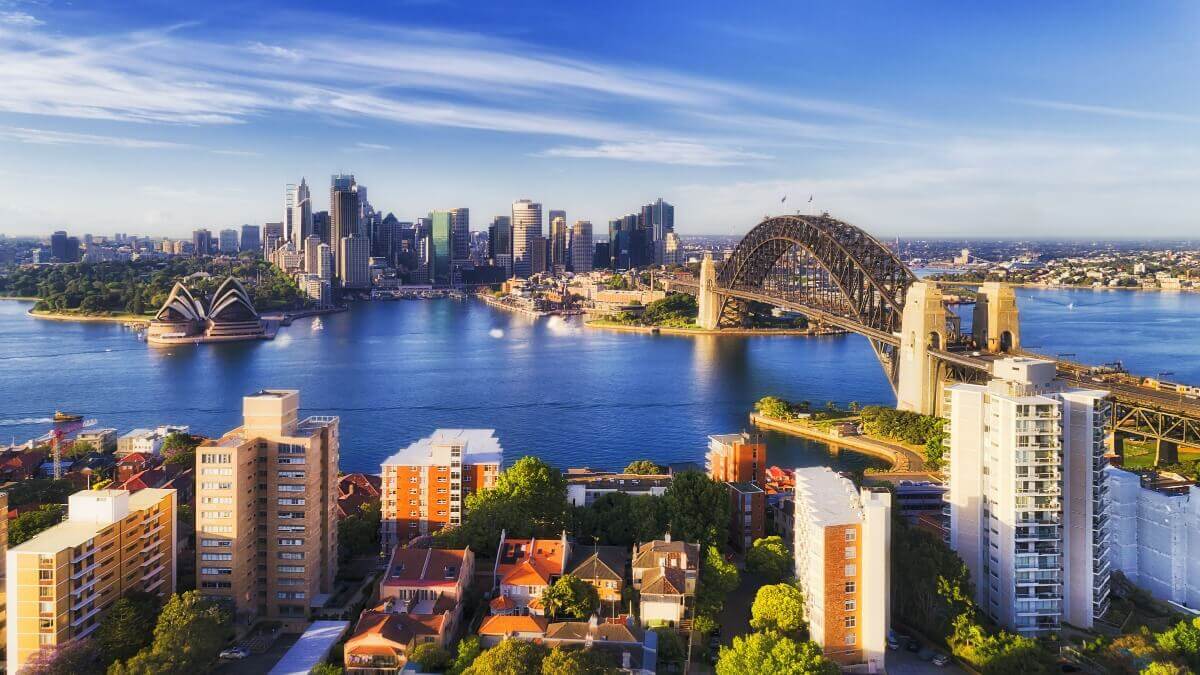
Having a home in Australia is a dream for many expats. But if you need financing, which most people do, then you'll need to understand how to get a mortgage in Australia as a foreigner.
Finding an expat mortgage isn't easy in Australia, so you should be prepared to seek local help and face higher costs than you might if you were a local - especially if you don’t hold long-term resident status.
However, owning your dream home in Australia is still achievable. This handy guide covers which banks and brokers offer mortgages and home loans in Australia to non-residents, the paperwork you'll need to get your loan, the legal ins and outs, and what it might cost.
US citizens may be able to get an Australian mortgage, but approval depends on the lender and your finances. If Australian law treats you as a foreign person, you will generally need approval before buying residential property, regardless of value.4
Your position may differ if you are an Australian citizen living abroad, a New Zealand citizen, an eligible permanent resident, a temporary resident, or a foreign non-resident. Confirm your foreign-investment status before making an offer.
Foreign borrowers may face fewer lender options, larger deposit requirements, higher rates, or extra documentation.
Foreign persons can buy some residential property in Australia, but strict rules apply. The current policy generally prohibits foreign investors from buying established dwellings from April 1, 2025 through June 30, 2029, subject to limited exceptions.4
Foreign investment is generally directed toward new or near-new dwellings and vacant residential land for development. Approval, application fees, development conditions, registration, vacancy fees, state or territory taxes, and other obligations may apply.4
You may still apply for a mortgage, but lender approval does not replace foreign-investment approval or other legal requirements. Consider advice from an Australian conveyancer or lawyer before signing a contract.
Many different types of mortgages are available in Australia, but there are limited choices for foreign buyers. That said, typically, you can get a fixed-rate or a variable-rate mortgage:
Another option you might see, especially if you qualify as a first-time buyer in Australia, is a hybrid option, which has an introductory offer of a discounted variable rate, before moving onto the bank’s SVR.
This is sold as a ""honeymoon offer"" for new customers but might end up costing more overall as the SVR isn’t necessarily the best rate available.
It’s a good idea to get some specialist advice from a qualified financial advisor or mortgage broker who can explain the options available to you - especially as a foreign buyer, who has a limited borrowing power in Australia.
Lender policies for foreign income, residency status, property type, and loan-to-value ratios change often. Some major banks do not accept every foreign-buyer profile, so compare current eligibility before applying.
You can ask banks directly or use an Australian-licensed mortgage broker. Starting points include:
Listing a provider here is not a recommendation or a guarantee of eligibility.
If you struggle to find a mortgage locally, don’t forget that you might be able to take out a mortgage in your home country or use an international mortgage lender and use the funds to buy a property in Australia. Again, taking qualified legal advice is essential if you’re considering this.
Since getting a mortgage in Australia as a foreigner is complicated, it's a good idea to talk to a mortgage broker to see what your options are. You can also try to arrange a mortgage directly with your chosen bank, but that's the harder option.
A mortgage broker will have access to a large number of different lenders’ policies and offers, so you'll have a better chance of finding the best deal for you.
Read further:
Foreign buyers often need a larger down payment than Australian residents, but there is no single deposit or interest rate that applies to every non-resident mortgage. The amount depends on the lender, residency status, visa, income currency, property, and loan-to-value ratio.
Ask lenders or a licensed broker for current written terms. Do not rely on old rate or deposit examples when setting your budget.
Budget for costs that may include:
Rules and amounts vary, so calculate them for the exact property and jurisdiction.
If you’re trying to arrange your home purchase before moving to Australia, paying fees and incidental costs will be difficult unless you’ve already opened a local Australian bank account. Even then, if your main account is outside of Australia, you might need to send money to yourself from abroad to pay fees.
If you do, it’s important to check what you’ll be charged when you make an international money transfer. Compare the total cost of sending a large amount, including transfer fees and any exchange-rate markup. A transfer advertised as fee-free may still use an exchange rate that differs from the mid-market rate.
Now that we covered some of the basics, the only question left is: how to send money to pay for your property overseas?
Wise offers you a quick, secure and transparent way of sending money to Australia. Wise uses the mid-market exchange rate for currency conversion and shows the applicable fee before you confirm the transfer.6
With a Wise Account, eligible customers can hold 40+ currencies, get account details for select currencies, and use the Wise card in most places where debit cards are accepted.6
Please see Terms of Use for your region or visit Wise Fees & Pricing for the most up-to-date pricing and fee information
Before you apply for a mortgage in Australia, it's important to understand what you're getting into and how to increase your chances of approval. Here are a few tips.
The exact paperwork you'll need will depend on the bank and broker you use. However, you can expect to be asked for the following:
- Your passport or another valid form of ID
- Proof you qualify to buy a property under FIRB rules
- Visa or residence documents, if relevant to your application
- Documents to prove you're creditworthy (credit check, bank statements, proof of your wages, tax returns for the last three years, or a letter from your employer)
- Documents to prove the affordability of the mortgage (household cash flow statements, utility bills, or bank statements)
All of these documents should be provided to the bank to get a mortgage pre-approval, which means that they agree on how much they would lend you if you find a suitable property.
Once you have an offer accepted on a home you’ll have to sort out more paperwork, such as FIRB approval for the specific property.
To get a mortgage in Australia, you’ll generally need to follow these steps:
Step 1. Choose a mortgage broker or lender
Getting a mortgage in Australia as a foreigner is complicated, so an experienced broker will increase your chances of success.
Step 2. Check foreign-investment eligibility
Check whether the property type is available to you and whether you must apply for approval. Established dwellings are generally prohibited for foreign investors through June 30, 2029.
Step 3. Complete a financial assessment
Work with your broker to determine how much you can borrow based on your income and Australian lending criteria.
Step 4. Seek mortgage pre-approval
You'll need proof of income, bank statements, identification, visa documentation, and other paperwork.
Step 5. Search for an eligible property
Look for properties that meet the current foreign-investment rules, typically new or near-new dwellings or vacant land for development.
Step 6. Make a conditional offer
You may also have to pay a holding deposit when you do this.
Step 7. Submit the property and mortgage applications
If required, apply through the Australian Taxation Office before purchase and pay the application fee. Submit your complete mortgage application to the lender.
Step 8. Complete the legal process
Choose a conveyancer who will help with the legal aspects of the purchase.
Step 9. Settle the purchase
Once your mortgage is approved, your conveyancer will coordinate the settlement to register you as the property owner.
Mortgage approval time varies by lender, application quality, valuation, and borrower profile. Foreign buyers should also allow time for any required foreign-investment approval, legal review, and settlement conditions.
If you're set on buying a house in Australia, you should be prepared for stricter lending criteria, higher interest rates, and larger down payment requirements than Australian residents.
It's possible to get an Australian mortgage - especially if you work with a good broker - but you could also explore applying for a mortgage in the US or working with an international lender.
When you’re ready, move money where it matters with Wise. You can send supported transfers to AUD, hold supported currencies, and review the fee and mid-market exchange rate before sending, including for large amounts.
Get a Wise Account
in minutes 💰
Sources
Sources checked 09.09.2026
*Please see terms of use and product availability for your region or visit Wise fees and pricing for the most up to date pricing and fee information.
This publication is provided for general information purposes and does not constitute legal, tax or other professional advice from Wise Payments Limited or its subsidiaries and its affiliates, and it is not intended as a substitute for obtaining advice from a financial advisor or any other professional.
We make no representations, warranties or guarantees, whether expressed or implied, that the content in the publication is accurate, complete or up to date.

Can US citizens buy real estate in Montenegro? Discover progressive property taxes, foreign ownership restrictions, and how to safely secure a deed.

Can foreigners own land in Thailand? Learn what US buyers can do, key risks, typical costs, and how to handle large international transfers for property.

Can US citizens buy real estate in Cyprus? Learn about Council of Ministers approval, property taxes, and the complete buying process in our guide.

Foreigners owning land in the Philippines: a practical guide for US buyers on property rules, buying steps, costs, and large international transfers.

Can US citizens buy real estate in Switzerland? Learn about strict Lex Koller restrictions, residence permit rules, cantonal quotas, and the buying process.

Renovating a house in Sicily? Plan scope, budget, and living considerations for US buyers-plus how to manage international transfers for renovation payments


